Storm damage roof inspection in Orlando
We photograph what the storm did, write it down in a report you keep, and price the repair to you directly. We don’t knock on doors after a storm, and if the roof is fine, the report says so.
Is this you?
Signs the storm got your roof
Shingles in the yard
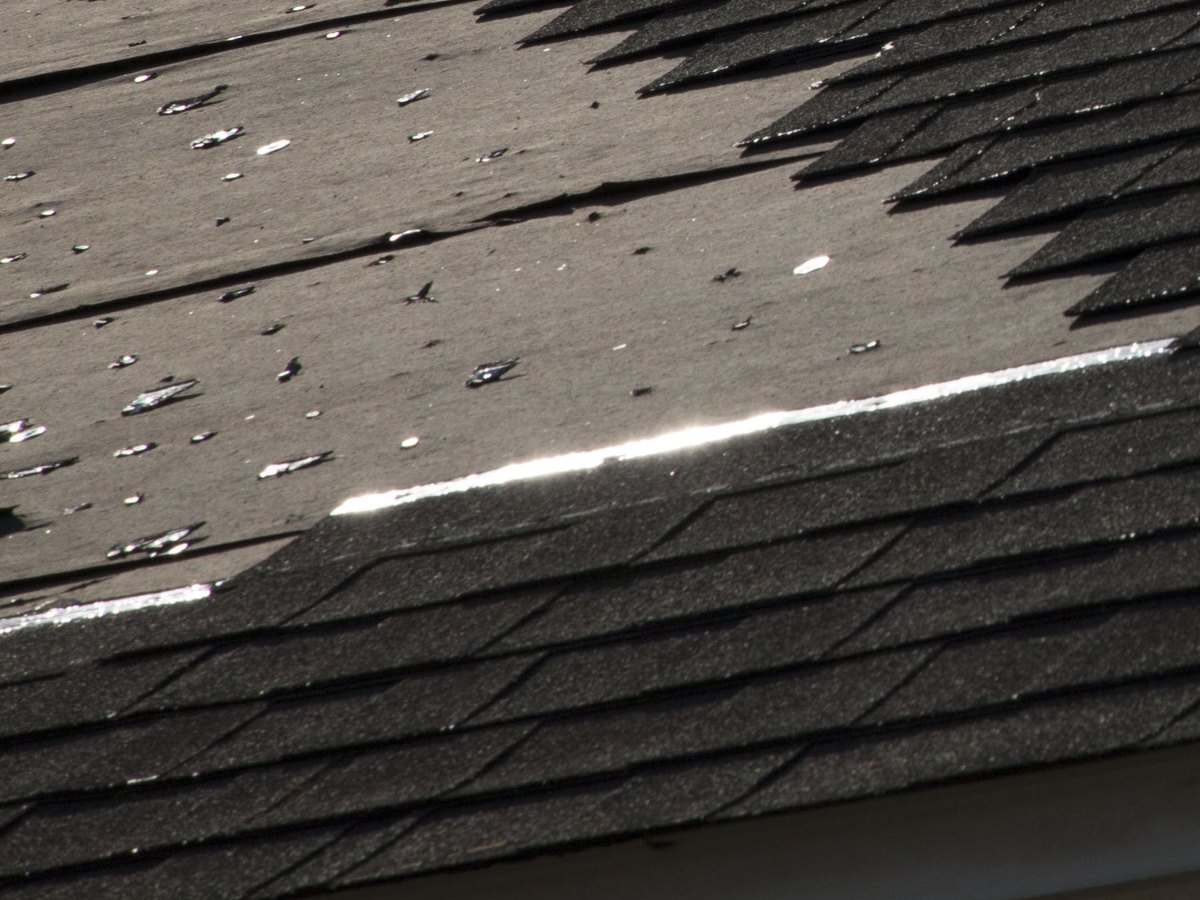
Missing or lifted shingles, usually on the side the wind came from.
Dented vents or gutters
The soft metal bruises first. Hail and debris show there before the shingles.
A new stain after the storm
Water found a way in. The attic shows us where.
Calm, not a sales pitch
We write down what is actually there
After a storm there are two kinds of roofer in the street: the ones looking at roofs and the ones looking for signatures. We come when you call, read the roof, and photograph it.
Some visits end with a page that says there’s very little wrong. That page is worth having too.
How we do it
What we look at, in order
Soft metals first
Vents, gutters and drip edge show hail and debris before shingles do.
Every slope
Lifted, creased and missing shingles, marked and photographed.
The attic underneath
Fresh water marks and wet insulation, photographed.
Written down
A report you keep, including when we find very little.
What it costs
What decides the cost of storm repairs
We price the repair to you directly, in writing, line by line.
How much came off
A few shingles is a repair. A whole slope may not be.
What got wet
Wet deck or insulation adds to the job, and gets photographed.
What we don’t do
Insurance claims. We’re a repair and re-roof company and price the work to you.
The details
For the people who want every step
What we look at, and in what order
The soft metals first, because they bruise before shingles tear and they are the honest witness. Aluminum vent housings, the gutter apron, the drip edge and the gutters themselves take hail and debris visibly. If those are clean, the story about catastrophic hail damage to the shingles gets harder to tell.
Then the windward slopes for creased tabs — a shingle that has been lifted and folded back carries a horizontal crack line across the mat even after it lies back down, and that shingle will fail whether or not it is loose today. Then the ridge and hip cap, which goes first in wind. Then every penetration, because a boot that has been lifted is a leak next month. Then the attic, for wet insulation and daylight.
Insurance claims: what we don’t do
We are a retail roofing company. We inspect, write down what we find, and price the repair or the re-roof to you directly. We do not file, negotiate or handle insurance claims, and we do not act for you with an insurer.
In Florida, negotiating or settling a claim on a homeowner’s behalf is public adjusting, and it requires a license a roofer does not hold. If a contractor offers to “handle the whole claim for you”, ask whether they are a licensed public adjuster.
And we will not touch your deductible. Florida law does not allow a contractor to waive, rebate, absorb or otherwise pay a residential property insurance deductible. An offer to “take care of the deductible” tells you what the rest of that company’s paperwork is going to look like.
The 25 percent rule, which is not as simple as people say
You will hear that if more than a quarter of a roof is damaged in any twelve months, the whole thing has to be brought up to current code. That was the plain rule for a long time. The exemptions changed in 2022, and there is now a path where a roof built to a recent edition of the Florida Building Code can have the damaged portion repaired rather than the whole roof replaced.
Whether that applies to your house depends on when the roof was permitted, so the honest answer is: ask whoever tells you the rule to show you the code section and the permit history for your address. We will show you ours. Nobody should be quoting you a whole roof on the strength of a rule of thumb they have not looked up.
If it is actively leaking
Call the number. Temporary cover to stop water coming in is a legitimate emergency measure and it should be done properly — fastened, lapped uphill, and off the ridge — not a tarp with concrete blocks on it that funnels water into a different room. It also should not be presented as a repair, and it should not require you to sign anything about the permanent work.
And if the roof is fine
We write that down too. A storm report that says the vents are undamaged, the cap is intact, there are no creased tabs and the attic is dry is a genuinely useful document to have on file, and it costs you the same as any other look: nothing.
After a storm
Looked at firstSoft metals — vents, gutter apron, drip edgeThenWindward slopes for creased tabsThenRidge and hip cap, every penetration, the atticWe willWrite a condition report you keepWe will notFile, negotiate or handle an insurance claimWe will notWaive, rebate or absorb your deductible. Illegal in FloridaWe will notKnock on your door after a storm25% ruleAsk for the code section and your permit historyQuestions
What people ask us about this
Do you handle insurance claims?
No. We’re a repair and re-roof company and price the work to you directly. Negotiating a claim for you is public adjusting, which needs a license a roofer doesn’t hold.
Can you cover my deductible?
No. In Florida a contractor may not waive, rebate or absorb an insurance deductible. Be careful of anyone who offers.
It is leaking right now. What should I do?
Put a bucket under a drip and move what’s underneath. If the ceiling is sagging or bulging, leave the room and call. Please don’t go up on the roof or a ladder.
What if the roof is fine?
Then the report says so, and there’s nothing to sell you.
Get a straight answer about your roof.
Tell us what it’s doing. We’ll look at the roof and the attic and put it in writing.
Other work